
Direct Answer
Exponential Moving Average (EMA) is a moving average that gives more weight to recent observations while retaining exponentially decaying influence from older data. A higher reading generally means recent prices have pulled the weighted average upward; a lower reading generally means recent prices have pulled the weighted average downward. The main limitation is that the faster response comes with more sensitivity to noise and whipsaws.
Exponential Moving Average (EMA): Formula, Meaning, Signals, Examples and How to Use It
How Is Exponential Moving Average Calculated?
The Exponential Moving Average is a moving average that weights recent prices more heavily than older ones, with weights that decay by a constant factor. Each new value blends the latest price with the prior EMA, so no data ever fully drops out.
Formula: EMA(t) = alpha * Price(t) + (1 - alpha) * EMA(t-1), with alpha = 2 / (n + 1)
Inputs:
- A price series, most often the close
- Period n (9, 20, 50 and 200 are commonly used)
- A starting EMA value, often the simple average of the first n prices
Worked example. With n = 9 (alpha = 0.2), a new price of 105 and a prior EMA of 100, the new EMA is 101.00. The inputs are illustrative numbers, not market data.
Reading it. The line is read as a smoothed price level: price above a rising EMA describes an uptrend and price below a falling EMA a downtrend. Shorter periods follow price closely, while longer ones respond slowly and are often used as reference levels.
Limits. Faster response comes with more sensitivity to noise, so short EMAs produce frequent crossings in sideways markets. Because it is built from past prices it always lags, and results depend on the chosen period and starting value.
Indicator snapshot
| Attribute | Value |
|---|---|
| Abbreviation | EMA |
| Category | Trend |
| Creator / origin | No single modern originator |
| Primary inputs | Price/volume/market data as applicable |
| Common settings | Common periods include 9, 20, 50 and 200 |
| Output | Line/scalar |
| Typical range | Varies |
| Primary purpose | Describe trend direction, persistence, strength, or a smoothed price reference. |
| Main limitation | The faster response comes with more sensitivity to noise and whipsaws. |
What is Exponential Moving Average?
Exponential Moving Average is a moving average that gives more weight to recent observations while retaining exponentially decaying influence from older data. It should be treated as a transformation of observable market data, not as an independent source of truth. The useful question is not whether the indicator is “bullish” or “bearish” in isolation, but what specific market property it measures, which assumptions enter the calculation, and whether that information is already duplicated by another tool on the chart.
For Swoopr, the canonical profile should separate definition, calculation, interpretation and decision use. That keeps readers from collapsing a descriptive metric into a trading strategy. An indicator can describe trend, momentum, volatility, participation, positioning or risk without providing a complete entry, exit, sizing or portfolio decision.
What does it measure and why is it used?
Describe trend direction, persistence, strength, or a smoothed price reference. The practical value is repeatability: the same inputs and formula can be applied across a defined dataset, allowing users to compare readings through time or across instruments when the calculation convention is held constant.
The calculation can still be misleading if the data source, session, adjustment method, smoothing rule or parameter set changes. Two platforms can legitimately report different readings while using different assumptions, so check which conventions a chart uses.
Formula
EMAt = Pricet × k + EMA_(t−1) × (1−k), where k = 2/(N+1)
Calculation discipline
- Fix the instrument, timeframe and session before computing the indicator.
- Use one documented price/volume source and one corporate-action convention.
- State every lookback, smoothing method and reset rule.
- Handle missing data and zero denominators explicitly.
- Reproduce at least one worked example from raw inputs during QA.
- Compare the implementation with a second independent calculation before publication.
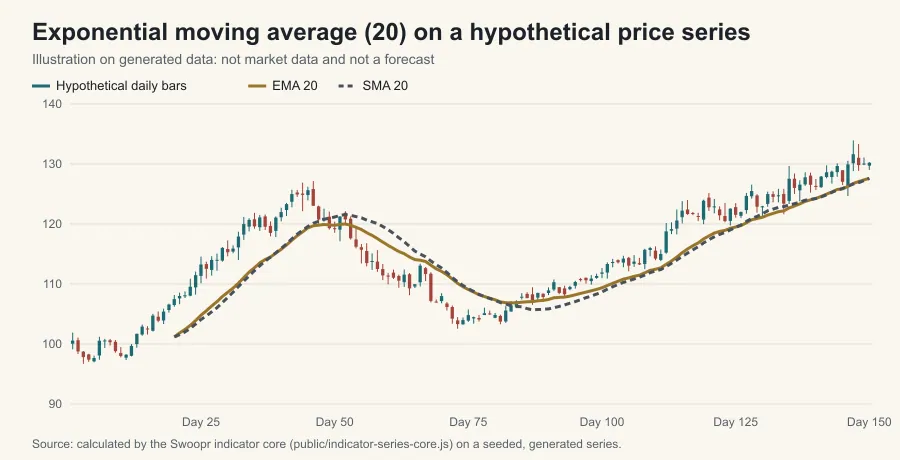
How to read Exponential Moving Average
A higher reading generally means recent prices have pulled the weighted average upward. A lower reading generally means recent prices have pulled the weighted average downward. That interpretation is descriptive, not predictive. The same numerical state can lead to different outcomes in a strong trend, quiet range, event-driven gap or illiquid market.
Bullish, bearish and neutral context
A bullish interpretation is appropriate only when the reading lines up with the indicator's actual job. For a trend tool, that means direction or trend persistence; for a momentum tool, it means stronger upside momentum; for a volatility measure, “higher” is not bullish at all:it only means larger expected or realized movement. A generic bullish or bearish label therefore does not fit a direction-neutral indicator.
A neutral state should be defined when the indicator does not provide enough evidence for its intended job. This is especially important for bounded oscillators near mid-range, volatility gauges near historical medians, or spread measures near long-run norms.
Common settings
The common reference is Common periods include 9, 20, 50 and 200. This is a starting convention, not a universally optimal parameter. Shorter lookbacks generally respond faster and produce more state changes; longer lookbacks smooth noise but react later. Parameter selection should be tied to the intended decision horizon, then tested over multiple instruments and regimes rather than optimized to one historical period.
Worked hypothetical interpretation
Suppose a researcher calculates Exponential Moving Average with the documented settings across a liquid security and observes a material change in the reading. The first step is to state what changed in the underlying input. The second is to ask whether price structure, volume, volatility or the benchmark environment confirms that interpretation. The third is to define what observation would invalidate it. Only after those steps should the indicator feed a strategy rule.
This sequence prevents a common error: treating the indicator output as if it arrived independently of the price, volume, options or market data used to calculate it.
Best and weak market conditions
Exponential Moving Average (EMA) is most useful when the market property it measures is actually relevant to the decision. It is weakest when the regime changes faster than the lookback, the market is illiquid, the input data are incomplete, or the chosen parameter set is mismatched to the timeframe. A trend indicator tends to struggle in ranges; a mean-reversion oscillator can remain extreme during persistent trends; volume-based measures can break when venue coverage changes; options and on-chain measures can be provider-specific.
Strengths
- A recursive formula needs only the prior EMA and the new price, so it is cheap to update bar by bar.
- Exponential weights make the line react to a price change sooner than a simple moving average of the same period.
- Reproducible when the formula and data convention are fixed.
Weaknesses and false signals
- The faster response comes with more sensitivity to noise and whipsaws.
- Parameter changes can alter timing and classification.
- Correlated indicators can create false confidence by repeating the same underlying information.
- Historical relationships can fail after market structure or volatility regimes change.
- Backtests can be overstated by look-ahead bias, survivorship bias, unrealistic fills or omitted transaction costs.
Combining Exponential Moving Average with other indicators
The strongest combination usually pairs different input families rather than similar formulas. Before adding another indicator, identify the specific error it is supposed to catch and measure how often the two signals disagree. High agreement between two price-only oscillators is not necessarily confirmation; it can be arithmetic redundancy.
Related entities for this profile include: Aroon, Average Directional Index, Choppiness Index, Ichimoku Cloud, MACD, Parabolic SAR.
When not to use it
Do not use Exponential Moving Average as a standalone forecast or as a substitute for position sizing, liquidity checks, execution planning or fundamental research when those are relevant to the decision. Avoid publishing “best settings” without a defined asset universe, timeframe, cost model and out-of-sample validation. If the indicator depends on proprietary or provider-specific methodology, the provider's own documentation is the authority on how it is calculated.
Practical checklist
- [ ] What exact question is the indicator answering?
- [ ] What data series, session and adjustments are used?
- [ ] What parameters and smoothing rules are fixed?
- [ ] Is the indicator bounded, unbounded or price-denominated?
- [ ] Does a second indicator add independent information?
- [ ] What market regime is present?
- [ ] What would invalidate the interpretation?
- [ ] Have slippage, costs and execution constraints been considered?
- [ ] Has the calculation been independently reproduced?
Frequently asked questions
Is Exponential Moving Average a buy or sell signal?
No. It is an analytical measure. A trade still needs a hypothesis, trigger, invalidation rule, position size, exit logic and realistic execution assumptions.
What is the best setting for Exponential Moving Average?
There is no universal best setting. Start with the conventional reference (Common periods include 9, 20, 50 and 200) and test nearby values across instruments, regimes and out-of-sample periods. Favor stable parameter regions over one historical winner.
Can Exponential Moving Average be used by itself?
It can describe its specific market property by itself, but using it alone generally leaves other important dimensions:direction, regime, participation, valuation, liquidity or risk:undefined.
Does Exponential Moving Average work on every timeframe?
The calculation may be portable, but behavior is not. A 14-period reading on a five-minute chart describes a very different market window from the same setting on a daily chart. Validate the exact timeframe.
Why does Exponential Moving Average give false signals?
False signals arise from lag, noise, regime changes, parameter sensitivity, data conventions and the fact that market participants react to new information after the reading is calculated.
How should Exponential Moving Average be backtested?
Write rules before testing, use point-in-time data, include delisted securities where relevant, model realistic fills and costs, reserve a validation sample, break results out by regime and compare with a simpler baseline.
Related Swoopr content
- Parent hub: Trend Indicators
- Related guide: SMA vs. EMA: Moving Averages Explained
- Related indicators: Aroon, Average Directional Index, Choppiness Index, Ichimoku Cloud, MACD, Parabolic SAR
Sources and further reading
Editorial and risk note
This page is educational content, not individualized investment advice. It does not imply guaranteed prediction, accuracy or outperformance.
Frequently Asked Questions
Is Exponential Moving Average a buy or sell signal?
No. The line is read as a smoothed price level: price above a rising EMA describes an uptrend and price below a falling EMA a downtrend. Faster response comes with more sensitivity to noise, so short EMAs produce frequent crossings in sideways markets. A trade built on it still needs a trigger, an invalidation rule, a position size and realistic execution assumptions.
What is the best setting for Exponential Moving Average?
Exponential Moving Average takes these inputs: a price series, most often the close; period n (9, 20, 50 and 200 are commonly used); a starting EMA value, often the simple average of the first n prices. There is no universal best setting for the tunable ones, so test them across instruments, regimes and out-of-sample periods and favor stable parameter regions over one historical winner.
Can Exponential Moving Average be used by itself?
Faster response comes with more sensitivity to noise, so short EMAs produce frequent crossings in sideways markets. Because it is built from past prices it always lags, and results depend on the chosen period and starting value. For that reason it is read next to measures of direction, participation, valuation, liquidity and risk, not alone.
Does Exponential Moving Average work on every timeframe?
The calculation (EMA(t) = alpha * Price(t) + (1 - alpha) * EMA(t-1), with alpha = 2 / (n + 1)) can be run on any bar size, but behavior is not portable: a reading on a five-minute chart describes a very different market window from the same reading on a daily chart. Validate the exact timeframe before relying on it.
Why does Exponential Moving Average give false signals?
The first values depend on the seed used, and the effect of that seed fades only gradually, so early readings differ between platforms. A single outlier price keeps a small weight in the average for many bars, so a spike leaves a lingering trace in the line. Lag, noise and regime changes add to this, because market participants react to new information after the reading is calculated.
How should Exponential Moving Average be backtested?
Rebuild Exponential Moving Average from a price series, most often the close using point-in-time data, write the rules before testing, include delisted securities where relevant, model realistic fills and costs, reserve a validation sample and compare with a simpler baseline.