
Direct Answer
Williams %R (%R) is a bounded momentum oscillator measuring where the latest close sits relative to the highest high and lowest low over a lookback. A higher reading generally means values near 0 mean the close is near the top of the recent range; a lower reading generally means values near −100 mean the close is near the bottom of the recent range. The main limitation is that extreme readings can persist during strong trends and do not by themselves imply reversal.
Williams %R (%R): Formula, Meaning, Signals, Examples and How to Use It
How Is Williams %R Calculated?
Williams %R, developed by Larry Williams, measures where the latest close sits relative to the highest high and lowest low of the last n bars. It runs from 0 at the top of the range to -100 at the bottom, and is the fast stochastic reflected onto a negative scale.
Formula: %R = -100 * (HighestHigh(n) - Close) / (HighestHigh(n) - LowestLow(n))
Inputs:
- High, low and close for each bar
- Lookback n for the range (14 is a common setting)
Worked example. With a highest high of 120, a lowest low of 100 and a close of 108, Williams %R is -60.0. The inputs are illustrative numbers, not market data.
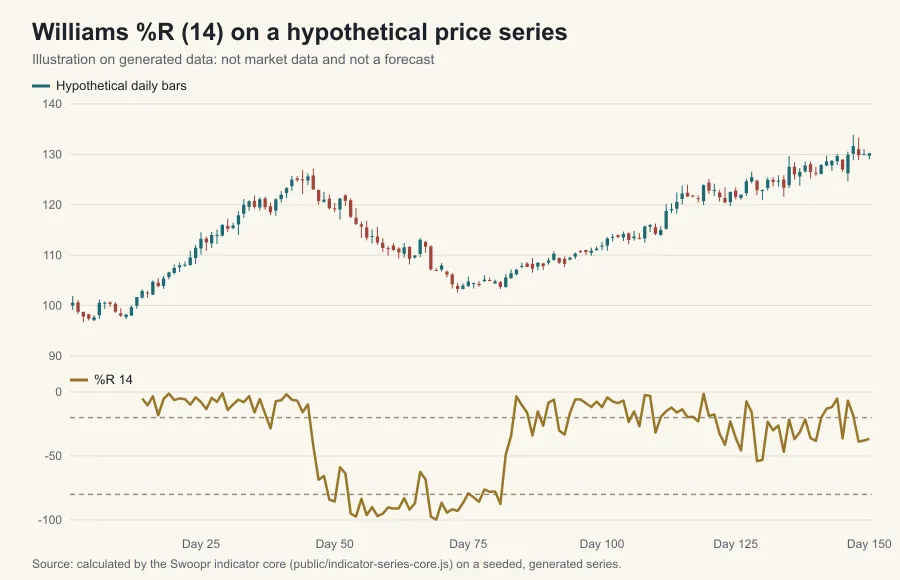
Reading it. Values near 0 mean the close is near the top of the recent range, and values near -100 mean it is near the bottom. Readings above -20 and below -80 are the conventional marks for the upper and lower ends of the range. They show where the close sits, not that a turn is due.
Limits. Extreme readings can last through a strong trend and do not by themselves signal a reversal. Because the line is not smoothed, it moves with every new close and the sensitivity depends heavily on the lookback chosen.
Indicator snapshot
| Attribute | Value |
|---|---|
| Category | Momentum |
| Creator / origin | Larry Williams |
| Common settings | 14 periods common |
| Primary purpose | Measure the speed, persistence, or relative intensity of recent price movement. |
| Main limitation | Extreme readings can persist during strong trends and do not by themselves imply reversal. |
What is Williams %R?
Williams %R is a bounded momentum oscillator measuring where the latest close sits relative to the highest high and lowest low over a lookback. It is a transformation of market data, not an independent forecast. Its value comes from making one market property measurable and repeatable so the same rule can be compared through time or across instruments when the input convention stays fixed.
This profile is separate from any trading strategy. It explains what the measure does, how it is calculated, what its readings mean, where it fails, and what other evidence can complement it. Entry, exit, position sizing and portfolio construction belong to strategy or risk-management content.
Formula
%R = −100 × (HighestHighN − Close) / (HighestHighN − LowestLow_N)
Calculation requirements
- Define the asset, timeframe, session and data source before calculation.
- State lookback, smoothing, reset and initialization rules.
- Define behavior for missing values, zero denominators and warm-up periods.
- Reproduce a worked example from raw inputs.
- Compare the result with an independent implementation before publication.
How to interpret it
A higher reading generally means values near 0 mean the close is near the top of the recent range. A lower reading generally means values near −100 mean the close is near the bottom of the recent range. That is a description of the selected inputs, not a promise about what price will do next. Strong readings can persist, reverse, or become irrelevant when the market regime changes.
The neutral zone should be defined by the indicator’s job rather than a generic red/green treatment. Direction-neutral measures should never be visually labeled bullish solely because the number is high.
Settings and parameter sensitivity
A common reference is 14 periods common. Defaults are conventions, not universal optima. Shorter windows usually respond faster and create more state changes; longer windows smooth more history and react later. When multiple platform conventions exist, publish the exact one Swoopr uses and identify important alternatives.
Worked hypothetical example
Take a liquid instrument and compute Williams %R using the documented convention. If the reading moves materially, trace the change back to its raw inputs before assigning meaning. Then compare the reading with one independent information family such as volume, volatility, benchmark-relative performance or price structure. Finally, define what observation would invalidate the interpretation. This prevents the indicator from being treated as a standalone prediction engine.
Strengths
- Reproducible once the exact calculation is fixed.
- Suitable for screening, charting, research and comparative analysis.
- Forces the analyst to convert vague impressions into explicit rules.
- Can be evaluated against a simpler baseline and across regimes.
Weaknesses and false signals
- Extreme readings can persist during strong trends and do not by themselves imply reversal.
- Parameter selection can materially change signal timing.
- Platform conventions may differ even when the indicator name is the same.
- Correlated indicators can create false confidence rather than independent confirmation.
- Backtests can be overstated by look-ahead bias, survivorship bias, unrealistic fills and omitted costs.
Combining Williams %R with other indicators
Prefer a second measure that answers a different question. Related entities include Commodity Channel Index, Rate of Change, Relative Strength Index, Stochastic Oscillator, Awesome Oscillator, Balance of Power. Before calling two signals “confirmation,” test how often they disagree and whether the second measure changes out-of-sample decisions after costs.
When not to use it
Do not use Williams %R as a standalone buy/sell instruction or as a substitute for liquidity checks, risk sizing and execution planning. Avoid publishing optimized settings without a clearly defined universe, timeframe, cost model and validation period. Provider-defined indexes or metrics must use the provider’s disclosed methodology and licensing rules.
Practical checklist
- [ ] Exact question defined
- [ ] Data source/session fixed
- [ ] Formula and parameters documented
- [ ] Independent calculation reproduced
- [ ] Regime identified
- [ ] Redundant indicators removed
- [ ] Invalidation condition written
- [ ] Costs and execution assumptions included where relevant
Frequently asked questions
Is Williams %R a buy or sell signal?
No. It is an analytical measure. A decision still needs a hypothesis, trigger, invalidation rule, size and exit process.
What is the best setting?
There is no universal best setting. Start from the common convention (14 periods common), test nearby values, and prefer stable parameter regions over a single historical winner.
Can it be used by itself?
It can describe its specific market property, but a complete decision usually needs additional context from another information family.
Why can the reading differ between platforms?
Data feeds, session rules, smoothing, initialization, lookback and provider methodology can all differ. Check the exact convention a given platform uses.
Does it work on every timeframe?
The formula may transfer, but behavior changes with timeframe, liquidity, volatility and execution costs. Validate the exact use case.
How should it be backtested?
Write rules before testing, use point-in-time data, include realistic costs, reserve an out-of-sample period, break results out by regime and compare with a simpler baseline.
Related Swoopr content
- Parent hub: Momentum Indicators
- Related indicators: Commodity Channel Index, Rate of Change, Relative Strength Index, Stochastic Oscillator, Awesome Oscillator, Balance of Power
Sources and further reading
Editorial note
Educational content only. Do not imply guaranteed prediction, accuracy or outperformance. Any provider-specific methodology must be labeled as such and rechecked when the provider changes its methodology.
Frequently Asked Questions
Is Williams %R a buy or sell signal?
No. Values near 0 mean the close is near the top of the recent range, and values near -100 mean it is near the bottom. Extreme readings can last through a strong trend and do not by themselves signal a reversal. A trade built on it still needs a trigger, an invalidation rule, a position size and realistic execution assumptions.
What is the best setting for Williams %R?
Williams %R takes these inputs: high, low and close for each bar; lookback n for the range (14 is a common setting). There is no universal best setting for the tunable ones, so test them across instruments, regimes and out-of-sample periods and favor stable parameter regions over one historical winner.
Can Williams %R be used by itself?
Extreme readings can last through a strong trend and do not by themselves signal a reversal. Because the line is not smoothed, it moves with every new close and the sensitivity depends heavily on the lookback chosen. For that reason it is read next to measures of direction, participation, valuation, liquidity and risk, not alone.
Does Williams %R work on every timeframe?
The calculation (%R = -100 * (HighestHigh(n) - Close) / (HighestHigh(n) - LowestLow(n))) can be run on any bar size, but behavior is not portable: a reading on a five-minute chart describes a very different market window from the same reading on a daily chart. Validate the exact timeframe before relying on it.
Why does Williams %R give false signals?
With no smoothing, the line can jump between the two ends of its scale within a few bars in a volatile market. A window in which the highest high equals the lowest low gives a zero denominator, so the value is undefined for flat ranges. Lag, noise and regime changes add to this, because market participants react to new information after the reading is calculated.
How should Williams %R be backtested?
Rebuild Williams %R from high, low and close for each bar using point-in-time data, write the rules before testing, include delisted securities where relevant, model realistic fills and costs, reserve a validation sample and compare with a simpler baseline.