
Direct Answer
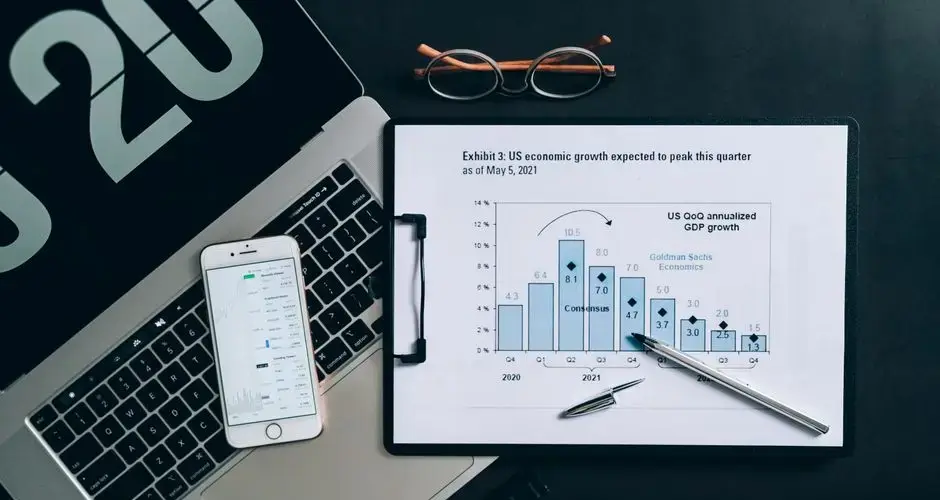
GDP, Gross Domestic Product, is the broadest single measure of economic output, defined as the total market value of all goods and services produced within a country's borders in a given period. In the US, the Bureau of Economic Analysis (BEA) computes GDP quarterly using the expenditure approach: GDP = C + I + G + (X − M), where C is personal consumption expenditures, I is gross private domestic investment, G is government spending, X is exports, and M is imports. Because GDP is published with a significant lag, the Advance estimate arrives approximately 4 weeks after the quarter ends, financial markets have largely priced GDP by the time it is released. The market-moving variable in a GDP release is the deviation from consensus (the economic surprise), not the level itself, and the components breakdown matters more than the headline rate.
Because GDP is backward-looking and heavily revised, leading indicators that predict future GDP growth have far more market impact in real time. The Conference Board's Leading Economic Index (LEI), the ISM Manufacturing and Services PMIs, the yield curve spread, and the Federal Reserve Bank of Atlanta's GDPNow nowcast are the most commonly used real-time growth proxies. Traders and portfolio managers who rely solely on GDP releases to assess growth are working with stale data; those who monitor the leading and nowcasting indicators have a materially better real-time view of where the economy is heading.
Key Takeaways
- GDP is an expenditure identity: C + I + G + (X−M). Consumer spending (C) is approximately 70% of US GDP, making consumer behavior the dominant driver. Investment (I), particularly business fixed investment and residential investment, is more cyclical and more leading.
- Three GDP releases per quarter: Advance (4 weeks after quarter end), Second Estimate (2 months after), and Third Estimate (3 months after). Average absolute revision from Advance to Final: approximately 1.3 percentage points of annualized growth.
- GDPNow nowcasts in real time: The Atlanta Fed's GDPNow model updates its GDP estimate every time relevant high-frequency data (retail sales, trade balance, construction spending, etc.) is released, tracking the underlying data that feeds the BEA's calculation in real time.
- PMIs lead GDP by 1-3 months: The ISM Manufacturing PMI reading above 50 indicates expansion; below 50 indicates contraction. The composite PMI (manufacturing + services) has a strong leading relationship with GDP growth direction.
- The LEI's sub-components matter: The Conference Board Leading Economic Index aggregates 10 components including the yield spread (10-year minus fed funds), ISM new orders, building permits, and consumer expectations. Consecutive months of LEI decline historically precede recessions.
- Inventories and net exports are volatile: Quarterly GDP growth can be dominated by inventory build (which is often reversed the following quarter) or trade balance swings. Stripping these out, looking at "final domestic demand" or "domestic private demand", provides a cleaner read of underlying growth.
- Real vs. nominal GDP: GDP growth reported in markets is always "real" GDP, nominal GDP deflated by the GDP price deflator (a broad inflation measure). Rising inflation inflates nominal GDP; high inflation with stagnant real output is the definition of stagflation.
- Two consecutive quarters of negative real GDP is a common recession heuristic, not the official definition: The NBER Business Cycle Dating Committee uses a broader range of indicators (income, employment, production, sales) and does not require two quarters of negative GDP for a formal recession declaration.
Core Concepts
GDP Components and the Growth Driver Hierarchy
Personal consumption expenditures (PCE) at approximately 68-70% of GDP is the dominant component and the most stable. Recessions do not typically occur because consumers suddenly stop spending, they occur because of a negative shock to investment, housing, trade, or a financial shock that then transmits to consumer spending. The leading edge of a growth slowdown almost always appears first in business investment (capital expenditures, inventories) and residential investment (housing starts, permits) before appearing in the consumption data.
Gross private domestic investment (I), at about 18% of GDP, is the most volatile GDP component and the most cyclical. Within investment, business fixed investment (equipment, structures, intellectual property) tracks corporate earnings expectations and borrowing costs. Residential investment (homebuilding) is the most interest-rate-sensitive component and tends to lead the business cycle, housing starts decline well before recession and recover before the employment picture improves.
Government spending (G), at roughly 17%, is relatively stable and countercyclical by design, fiscal deficits tend to expand during recessions as automatic stabilizers (unemployment insurance, Medicaid) kick in. Net exports (X−M) are highly variable and dominated by exchange rate movements and the relative growth rates of the US versus its trading partners. A stronger dollar tends to widen the trade deficit (more attractive imports, less competitive exports), subtracting from GDP growth.
Final domestic private demand, personal consumption plus business fixed investment plus residential investment, excluding government, inventories, and net exports, is the cleanest measure of underlying private sector economic momentum. Stripping inventories removes the most volatile and mean-reverting component; stripping government removes cyclical policy effects. Professional GDP analysts focus heavily on this "core" measure of growth.
The GDP Release Sequence: Advance, Second, Third Estimate
The BEA publishes GDP three times per quarter. The Advance estimate, released approximately 30 days after the quarter ends, is based on incomplete source data. Because the BEA has only about 50-70% of the underlying data for the quarter when it publishes the Advance, the initial estimate can be substantially revised. The Second Estimate (60 days after quarter end) incorporates more complete data for key components. The Third Estimate (90 days after quarter end) adds comprehensive data including full trade and service-sector surveys.
The average absolute revision from Advance to Third Estimate is approximately 1.2-1.4 percentage points of annualized GDP growth. The distribution of revisions is roughly symmetrical, no systematic tendency to revise up or down, but individual quarters can see revisions of 2-3 percentage points. During the 2008 financial crisis, early GDP readings initially showed modest growth that was subsequently revised to substantial contraction, dramatically understating the severity of the downturn in real time.
Annual comprehensive revisions, released each July for the prior 5 years, can re-benchmark entire years of GDP history. These revisions incorporate Census Bureau data, tax records, and administrative data sources not available quarterly. The 2013 comprehensive revision, for example, restructured how intellectual property investment was classified, which permanently raised the level of US GDP by approximately $560 billion and changed the measured productivity trend.
Nowcasting: GDPNow and Real-Time Growth Tracking
The Federal Reserve Bank of Atlanta publishes GDPNow, a real-time estimate of the current quarter's GDP growth that updates every 1-3 business days as new data arrives. The model mechanically replicates the BEA's methodology using the same underlying data series as they become available. When retail sales, industrial production, the trade balance, and construction spending are released, GDPNow updates its estimate accordingly.
GDPNow is not a forecast of what GDP will ultimately be. It is a nowcast of what GDP would estimate if the BEA were to compute it with the available data today. Because it uses the same methodology as the BEA, it tends to converge toward the Advance estimate as the quarter progresses and more data becomes available. Early in the quarter, with little underlying data, the GDPNow estimate can swing dramatically from week to week.
The New York Fed publishes a similar nowcasting model that uses a broader set of variables and a different statistical approach, producing a distribution of estimates rather than a point estimate. Financial markets watch both models, but the Atlanta Fed GDPNow is more widely cited in real-time market commentary because it updates more frequently and its methodology is more transparent. The two models' estimates frequently diverge by 1-2 percentage points early in the quarter and converge as data accumulates.
PMIs as the Most Market-Relevant Leading Indicators
Purchasing Managers' Indexes (PMIs) from ISM and S&P Global (formerly Markit) are diffusion indexes that survey purchasing managers about changes in business conditions. Each sub-component asks whether conditions improved, worsened, or stayed the same relative to the prior month; the index score is the percentage reporting improvement plus half the percentage reporting unchanged conditions. A reading above 50 indicates expansion; below 50 indicates contraction.
The ISM Manufacturing PMI is released on the first business day of each month (covering the prior month) and is the most market-moving PMI. The ISM New Orders sub-component is particularly watched as the most forward-looking element, a decline in new orders precedes a decline in overall production by 1-3 months. The prices-paid sub-component provides a real-time read on input cost inflation pressure, making PMIs simultaneously useful for growth and inflation analysis.
ISM Services PMI (released approximately 3 business days into each month) covers a larger share of the economy but historically receives slightly less market attention than manufacturing PMI. S&P Global publishes alternative manufacturing and services PMIs based on a different survey methodology and sample that can diverge from ISM. When ISM and S&P Global PMIs diverge significantly, traders investigate the composition differences (ISM is larger-company biased; S&P Global includes more smaller firms) to determine which is more representative of current conditions.
Worked Scenario
- Q1 setup: ISM Manufacturing PMI enters the quarter at 48.2 (contraction). S&P Global composite PMI is 52.1 (diverging, services-driven expansion). The Conference Board LEI has declined for 6 consecutive months. The yield spread (10-year minus 2-year) is inverted at -0.4%. GDPNow enters the quarter tracking +1.8% annualized.
- Within-quarter data: Retail sales for January disappoint (-0.8% MoM vs. -0.3% consensus). Trade deficit widens as imports surge. GDPNow falls from +1.8% to +0.7% over two weeks. Housing starts recover modestly. Business fixed investment data from capital goods orders (released as durable goods orders ex-defense, ex-aircraft) shows flat growth.
- Advance GDP release: Q1 GDP prints +0.4% annualized, a miss vs. the +1.0% consensus. Inventory liquidation subtracted 1.2 percentage points; final domestic demand grew +1.6%, showing the underlying demand picture was meaningfully better than the headline suggested.
- Market interpretation: Equities initially sell off 0.8% on the headline miss. Within 30 minutes, the component breakdown is analyzed: -1.2pp inventory drag is typically transient and often mean-reverting in the following quarter. Final domestic demand at +1.6% confirms consumer and business spending held up. Equities recover most of the loss; the 10-year yield declines 5 basis points as recession fears briefly rise then moderate.
- Leading indicator context: The simultaneous decline in LEI and inverted yield curve that precede this reading reinforce the caution signal. The scenario illustrates the critical distinction between weak GDP driven by inventory and trade swings (often transient) versus weak GDP driven by declining final domestic demand (the more durable recessionary signal).
Measurement Framework
| Measurement | Question to Answer |
|---|---|
| Final domestic private demand growth (GDP ex-inventories, trade, govt) | What is the underlying private sector growth momentum, stripped of volatile components? |
| GDPNow current-quarter estimate | Where is GDP tracking in real time given all available within-quarter data? |
| ISM Manufacturing PMI (especially New Orders sub-index) | Is the manufacturing sector in expansion or contraction, and is it leading or lagging? |
| Conference Board LEI 6-month change | Has the composite leading indicator been declining consistently enough to flag recession risk? |
| Advance vs. consensus GDP surprise | Did the economy grow faster or slower than expected? |
| GDP revision from Advance to Second Estimate | Was the initial read systematically high or low relative to complete data? |
Common Failure Modes
Treating Inventory-Driven GDP Swings as Demand Signals
Inventory accumulation and drawdown are the most volatile and least persistent contributors to quarterly GDP growth. A quarter with +3% GDP driven by +2pp of inventory build is far less impressive than headline suggests, inventory builds are often "accidental" (demand came in weak relative to production) and tend to be reversed in subsequent quarters. Similarly, an inventory liquidation quarter (-1pp inventory contribution) often masks strong underlying demand.
Always strip out the inventory contribution when interpreting GDP. Sustained final demand growth, particularly final private domestic demand, is the signal worth acting on. Inventory swings create noise that distorts the reading and reversal creates mean reversion in the subsequent quarter's headline.
Using GDP to Time Trades
GDP is a lagging, backward-looking measure. By the time Q1 GDP is released in late April, the market has already processed 13 weeks of higher-frequency data (payrolls, retail sales, industrial production, PMIs) that feed into the GDP calculation. The "GDP surprise", the deviation from consensus, typically reflects imperfect aggregation of high-frequency data rather than genuinely new information about the underlying economy. GDP releases occasionally produce large market moves, but they are less systematically predictable than the high-frequency data releases that precede them.
Use GDP to confirm or deny the narrative established by leading indicators, not to initiate new macro positions. The real positioning opportunities arise from the high-frequency data that leads GDP, retail sales, ISM, housing starts, and capital goods orders, where the information gap between release and market pricing is larger.
Ignoring the GDP Deflator in Nominal vs. Real Comparisons
GDP is reported in "real" (inflation-adjusted) terms, using the GDP price deflator, a broader inflation measure than CPI or PCE that covers all goods and services in the economy, including government purchases and investment. The deflator can differ substantially from CPI in periods when investment good prices or government service prices are moving differently than consumer prices.
In periods of high inflation, nominal GDP can grow rapidly even if real output is stagnant or falling. This distinction matters for equity analysis: corporate revenues are nominal, growing with both price and volume, while real GDP captures only the volume component. A company's revenue can grow 10% while real GDP stagnates if most of the revenue growth reflects pricing power rather than volume expansion.
Over-Relying on Two Quarters of Negative GDP as a Recession Definition
The popular definition of a recession, two consecutive quarters of negative real GDP growth, is a heuristic, not the official US definition. The NBER Business Cycle Dating Committee declares recessions based on a broad set of coincident indicators (employment, income, production, sales) evaluated for depth, diffusion, and duration. There have been periods of two consecutive negative GDP quarters that the NBER did not classify as recessions, and the NBER has declared recessions without two consecutive negative quarters (notably 2001).
Using the two-quarter rule as a position trigger will produce false signals. Use the NBER's own indicators (employment, production, real income, real sales) as recession trackers, supplemented by the Sahm Rule for real-time trigger identification. The two-quarter heuristic is useful shorthand for public communication but is not a reliable trading or allocation signal.
Frequently Asked Questions
What is the difference between GDP and GNP?
GDP (Gross Domestic Product) measures the total output produced within a country's geographic borders, regardless of whether the producing entity is domestic or foreign-owned. GNP (Gross National Product), now called GNI (Gross National Income), measures the total output produced by a country's residents, regardless of where the production occurs. For the US, GDP and GNP are very close because the US economy is relatively self-contained. For small, open economies with large foreign-owned sectors (like Ireland) or large overseas worker populations (like the Philippines), the gap between GDP and GNP can be substantial.
What is GDPNow and how accurate is it?
GDPNow is the Atlanta Federal Reserve's real-time GDP nowcasting model, updated every 1-3 business days as new within-quarter data arrives. Its accuracy depends on how far into the quarter it is: early in the quarter with little data, the model's estimate can swing by several percentage points. By the last 2-3 weeks before the BEA's Advance release (when most component data is available), GDPNow typically converges to within 0.5-1.0 percentage points of the eventual Advance release. It is not a forecast of future GDP, it replicates the BEA's methodology in real time. Available at atlantafed.org/cqer/research/gdpnow.
What is the Conference Board Leading Economic Index?
The Conference Board Leading Economic Index (LEI) is a composite index of 10 leading economic indicators: average weekly hours in manufacturing, average weekly initial claims for unemployment insurance, manufacturers' new orders for consumer goods, the ISM new orders index, manufacturers' new orders for capital goods, building permits, S&P 500 index changes, Leading Credit Index (a financial conditions proxy), interest rate spread (10-year minus fed funds), and average consumer expectations. Six or more consecutive months of decline, particularly when the decline is broad across sub-components, has historically preceded every US recession. Available at conference-board.org.
How is potential GDP different from actual GDP, and why does it matter?
Potential GDP is the estimated output the economy could produce if all resources were employed at their non-inflationary capacity. It is a measure of the economy's supply side rather than its current demand. The gap between actual and potential GDP is called the "output gap." A positive output gap (actual > potential) means the economy is running hot, demand exceeds supply capacity, which is inflationary. A negative output gap (actual < potential) means slack exists, which is deflationary. The CBO estimates potential GDP quarterly. The Federal Reserve's Monetary Policy Report routinely discusses the output gap as part of its inflation and growth assessment.
Why do ISM and S&P Global PMI sometimes give conflicting signals?
ISM and S&P Global PMIs survey different panels of companies with different industry weights and size biases. ISM historically overweights larger manufacturers and has a higher concentration of domestic-supply-chain-dependent industries. S&P Global's panel includes more smaller firms and more export-oriented companies. In months when large and small companies, or export and domestic companies, are experiencing different conditions, the two indexes diverge. Both are useful; significant persistent divergence between the two often points to sector or size segmentation worth investigating further.
What does it mean when the LEI has declined for 6 consecutive months?
The Conference Board's heuristic for an LEI recession signal is a decline in the 6-month change rate of the LEI, combined with broad-based weakness across the 10 components (not concentrated in one or two). Historically, when these conditions are met, a recession has followed within 3-12 months. The LEI is a probabilistic signal, not a deterministic one, it had a false positive in 2022-2023 when the LEI declined substantially but the recession did not materialize with the severity or timing implied by the signal. The inverted yield curve and weak housing activity components drove much of the 2022-2023 LEI weakness, while labor market indicators remained strong.
How does GDP relate to corporate earnings growth?
Nominal GDP growth (not real GDP) is the broadest measure of the revenue opportunity for the corporate sector. Over long periods, aggregate corporate earnings grow roughly in line with nominal GDP, approximately real GDP growth plus inflation. In any given cycle, corporate earnings grow faster than GDP during expansion (operating leverage) and fall faster during recession (same leverage in reverse). Profit margins expand when revenue growth outpaces input cost growth and compress when costs rise faster than prices. The share of GDP captured by corporate profits (the "profit share") is cyclical and mean-reverting over multi-decade periods.
What is the GDP price deflator and how does it differ from CPI?
The GDP price deflator measures the price level of all goods and services included in GDP, not just consumer goods. Unlike CPI, which uses a fixed basket of consumer-purchased goods and services, the GDP deflator is chain-weighted and covers investment goods, government purchases, and exports in addition to consumer goods. The deflator tends to show lower inflation than CPI because investment goods prices (technology, machinery) have fallen in real terms, pulling down the aggregate deflator relative to the consumer price basket. During inflationary periods, the deflator and CPI track more closely because services (included in both) dominate the pricing dynamics.
What is gross domestic income, and why does it diverge from GDP?
Gross domestic income measures the same total activity from the income side, summing wages, profits, rents and taxes, where GDP sums expenditure. In principle they are equal; in practice they are built from different source data and differ by a statistical discrepancy. When the two diverge persistently, one of them is mismeasuring, and the average of the two is sometimes used as a more reliable read. Divergences have been large enough at cycle turns to change the picture of whether growth was slowing.
References
- Bureau of Economic Analysis. GDP and Personal Income: Primary source for all GDP releases, methodological notes, and historical revisions.
- Federal Reserve Bank of Atlanta. GDPNow: Real-time GDP nowcasting model updated with every relevant data release.
- Institute for Supply Management. ISM Report on Business: Monthly Manufacturing and Services PMI releases.
- Conference Board. US Leading Economic Indicators: Monthly LEI release with component breakdown.
- Congressional Budget Office. Budget and Economic Outlook: Potential GDP estimates and output gap analysis.
Educational Disclaimer
This guide is for educational purposes only. GDP and leading indicator data is subject to revision. Do not make investment decisions based solely on this content. Trading involves risk of loss. Verify data with primary sources and consult a qualified financial professional before acting.