
Direct Answer
The S&P 500's price-to-earnings ratio has averaged approximately 15-17x over the past century. It peaked at approximately 123x in December 2009 (earnings temporarily depressed) and at 30-32x in March 2000 (dot-com bubble). The Shiller CAPE (10-year average earnings) has averaged approximately 16-17x and stood at approximately 35-38x in 2024, above the historical average.
S&P 500 P/E Ratio (Valuation) History
S&P 500 trailing P/E ratio at year end (selected years)
| Year | Trailing P/E (approx) | Shiller CAPE (approx) | Context |
|---|---|---|---|
| 1990 | 15x | 15x | Near long-run average |
| 1995 | 17x | 21x | Bull market expanding |
| 1997 | 25x | 28x | Dot-com enthusiasm building |
| 1999 | 30x | 44x | Dot-com peak valuation |
| 2002 | 31x | 22x | Earnings trough post-bust |
| 2007 | 20x | 27x | Pre-crisis expansion peak |
| 2009 | ~84x | 13x | Earnings trough; CAPE shows cheap |
| 2010 | 18x | 21x | Recovery underway |
| 2015 | 23x | 27x | Post-QE expansion |
| 2018 | 20x | 29x | Rate shock year-end selloff |
| 2019 | 25x | 31x | Pre-COVID peak |
| 2020 | ~38x | 33x | Earnings crash; prices held up |
| 2021 | 26x | 40x | Zero rates; peak CAPE |
| 2022 | 19x | 28x | Rate shock compression |
| 2023 | 23x | 32x | AI enthusiasm rally |
| 2024 | 27x | ~37x | Elevated vs. historical average |
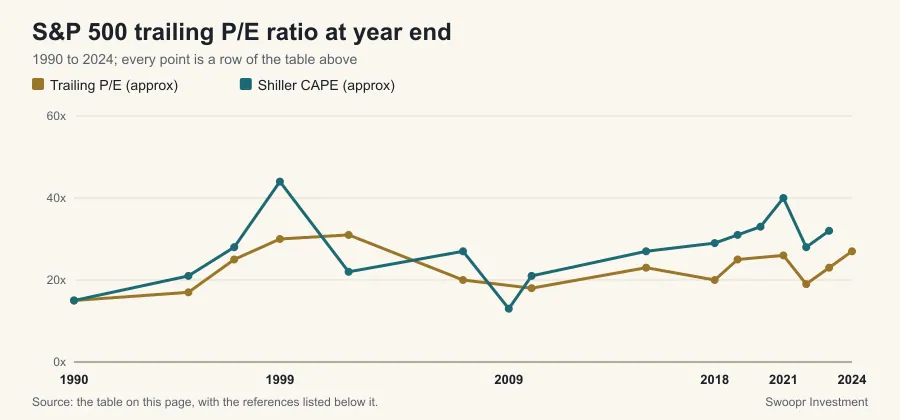
Source: Robert Shiller: Online Data (CAPE data). Data through 2024; last checked September 2026.
Frequently asked questions
What P/E ratio is considered normal for the S&P 500?
The long-run average trailing P/E for the S&P 500 is approximately 15-17x. However, 'normal' has shifted upward since the 1990s due to: lower interest rates (higher P/E justified when risk-free rates are low), higher corporate profit margins (technology companies earn more per dollar of revenue), and improved financial information reducing risk premiums. Many analysts argue the fair P/E in the 2020s is 18-22x due to structural changes. The Shiller CAPE's long-run average is approximately 16-17x, and above-average CAPE has historically predicted below-average forward returns.
Why was the P/E so high in 2009?
In 2009, earnings were depressed to near zero or negative for many financial companies due to loan write-downs from the financial crisis. The 'E' in P/E shrank dramatically even as stock prices stabilized and began recovering. This created a mechanically high P/E that was not indicative of stretched valuation but rather temporarily suppressed earnings. Using normalized earnings (as in the Shiller CAPE which averages 10 years of earnings) avoids this distortion: the Shiller CAPE in 2009 fell to approximately 13x, correctly identifying stocks as cheap relative to history.
Can high P/E ratios persist for years?
Yes. The U.S. market has traded at above-average P/E ratios since approximately 1992, with interruptions during the 2002 and 2008-2009 crashes when earnings recovered faster than prices. Japan provides a cautionary example: the Nikkei traded at 50-80x P/E in the late 1980s before a 30-year secular bear market. However, U.S. corporate governance, innovation, and earnings growth have supported higher-than-global-average valuations. The tension in 2024-2025: elevated CAPE suggests below-average forward returns, but timing the correction has been historically very difficult.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). S&P 500 P/E Ratio (Valuation) History. Swoopr Investment. https://www.getswoopr.com/tables/returns/sp500-pe-ratio-history/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.