
Direct Answer
The S&P 500 dividend yield has declined from approximately 5-6% in the 1950s-1970s to approximately 1.2-1.5% today. This reflects a shift toward share buybacks as the primary capital return mechanism and higher equity valuations. The yield has historically served as a rough valuation indicator.
S&P 500 Dividend Yield History
S&P 500 dividend yield at year end (selected years)
| Year | Dividend yield | Context |
|---|---|---|
| 1950 | 5.8% | Post-war; dividends primary return mechanism |
| 1960 | 3.4% | 1950s bull market raised prices |
| 1970 | 3.8% | Stagflation era; high yields |
| 1980 | 4.7% | High interest rates; value era |
| 1990 | 3.5% | Pre-buyback-era baseline |
| 1995 | 2.3% | Dot-com bull market begins |
| 2000 | 1.2% | Dot-com peak valuation; yield low |
| 2005 | 1.8% | Post-bust recovery; yields higher |
| 2010 | 1.8% | Post-crisis; dividends raised |
| 2016 | 2.1% | Higher payout era (low rates) |
| 2019 | 1.9% | Pre-COVID; rising buybacks |
| 2021 | 1.3% | Zero-rate era peak valuations |
| 2022 | 1.7% | Bear market raised yield |
| 2024 | 1.2% | Near historic lows; buybacks dominate |
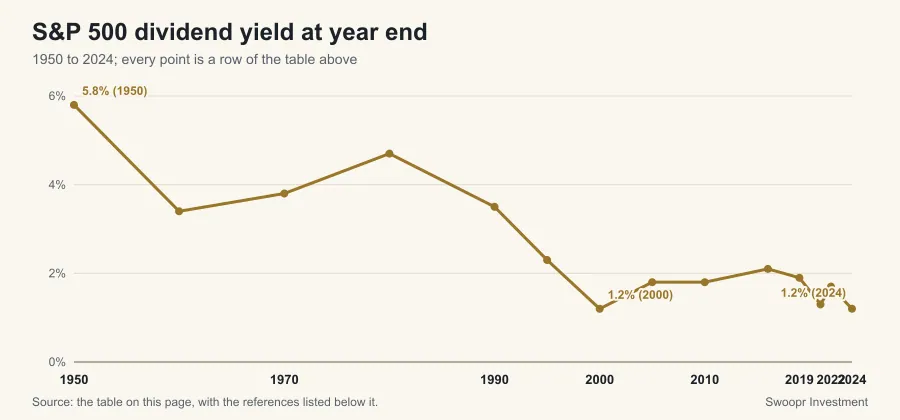
Source: St. Louis Fed: S&P 500 Dividend. Data through 2024; last checked September 2026.
Frequently asked questions
Why has the dividend yield declined so much since 1950?
Several structural shifts explain the dividend yield decline: (1) share buybacks replaced dividends as the primary capital return method after the 1980s (driven by favorable tax treatment and executive stock option incentives); (2) higher equity valuations (higher prices relative to dividends mechanically reduce yields); (3) growth of technology sector (non-dividend-paying growth companies now represent 25-30% of the index); (4) change in investor preference from income to total return. S&P 500 companies now return approximately equal amounts through dividends and buybacks.
Are share buybacks better than dividends?
Tax efficiency favors buybacks for most investors: dividends create immediate taxable income (even in taxable accounts), while buybacks allow capital gains deferral until shares are sold. From a total return perspective, buybacks and dividends are economically equivalent (both transfer value from the company to shareholders). Buybacks are more flexible (companies can stop them in bad times without the reputational damage of a dividend cut). Critics note that buybacks at inflated valuations destroy value; supporters note management has better information about intrinsic value than the market.
What is the dividend discount model?
The Dividend Discount Model (DDM) values stocks as the present value of all future dividends. The simplest form (Gordon Growth Model): Stock Value = Dividend / (Required Return - Dividend Growth Rate). If a stock pays a $2 dividend, grows at 5% per year, and you require a 10% return, the value = $2 / (10% - 5%) = $40. The DDM is most applicable to mature dividend-paying companies and utility/REIT sectors. For growth companies that pay no dividends (or minimal ones), the model either does not apply or requires estimating far-future dividends when the company matures.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). S&P 500 Dividend Yield History. Swoopr Investment. https://www.getswoopr.com/tables/returns/dividend-yield-history/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.