
Direct Answer
The SIMPLE IRA employee deferral limit for 2026 is $17,000, up from $16,500 in 2025. Workers age 50 to 59 or 64 and older can add a standard catch-up of $4,000 (total $21,000). Workers age 60-63 have an enhanced SECURE 2.0 catch-up of $5,250 (total $22,250). SIMPLE IRA limits are lower than 401(k) limits and available only to employers with 100 or fewer employees.
SIMPLE IRA Contribution Limits by Year
SIMPLE IRA contribution limits by year (2005-2026)
| Year | Employee Deferral | Catch-up (Age 50+) | Total with Catch-up |
|---|---|---|---|
| 2005 | $10,000 | $2,000 | $12,000 |
| 2006 | $10,000 | $2,500 | $12,500 |
| 2007 | $10,500 | $2,500 | $13,000 |
| 2008 | $10,500 | $2,500 | $13,000 |
| 2009 | $11,500 | $2,500 | $14,000 |
| 2010 | $11,500 | $2,500 | $14,000 |
| 2011 | $11,500 | $2,500 | $14,000 |
| 2012 | $11,500 | $2,500 | $14,000 |
| 2013 | $12,000 | $2,500 | $14,500 |
| 2014 | $12,000 | $2,500 | $14,500 |
| 2015 | $12,500 | $3,000 | $15,500 |
| 2016 | $12,500 | $3,000 | $15,500 |
| 2017 | $12,500 | $3,000 | $15,500 |
| 2018 | $12,500 | $3,000 | $15,500 |
| 2019 | $13,000 | $3,000 | $16,000 |
| 2020 | $13,500 | $3,000 | $16,500 |
| 2021 | $13,500 | $3,000 | $16,500 |
| 2022 | $14,000 | $3,000 | $17,000 |
| 2023 | $15,500 | $3,500 | $19,000 |
| 2024 | $16,000 | $3,500 | $19,500 |
| 2025 | $16,500 | $3,500 / $5,250 (age 60-63) | $20,000 / $21,750 |
| 2026 | $17,000 | $4,000 / $5,250 (age 60-63) | $21,000 / $22,250 |
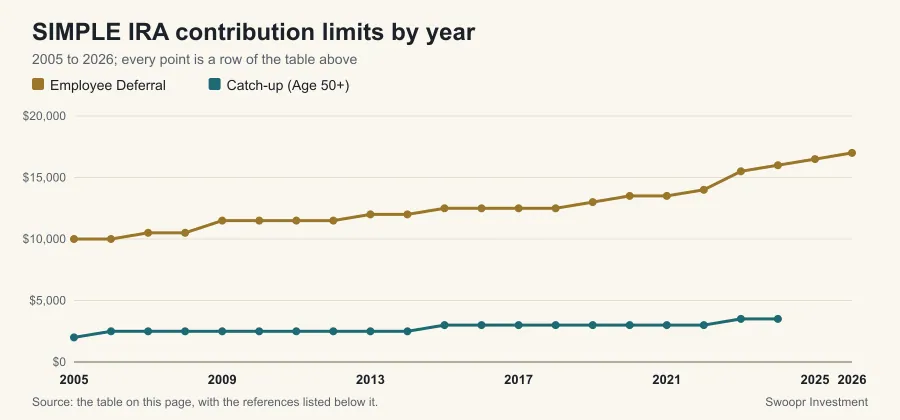
Source: IRS: SIMPLE IRA Plan FAQs - Contributions and IRS: 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500 (Notice 2025-67). Last verified: October 2026. Verify current-year figures at IRS.gov before making decisions.
Frequently asked questions
How does a SIMPLE IRA differ from a 401(k)?
A SIMPLE IRA has lower contribution limits than a 401(k) and is only available to employers with 100 or fewer employees. The employer is required to contribute, either matching dollar-for-dollar up to 3% of compensation or making a flat 2% non-elective contribution. Administrative costs are typically lower than a 401(k).
What is the employer matching rule for SIMPLE IRAs?
Employers have two options: match employee contributions dollar-for-dollar up to 3% of compensation (reducible to 1% in up to 2 of every 5 years with notice), or contribute a flat 2% of each eligible employee's compensation whether or not the employee contributes. Employees should verify which formula their employer uses to maximize their match.
Can employees over 50 contribute more to a SIMPLE IRA?
Yes. The standard catch-up for workers age 50 or older is $4,000 in 2026, bringing the total to $21,000. Workers age 60-63 have an enhanced catch-up of $5,250 (total $22,250) under SECURE 2.0. This enhanced catch-up is not available to those 64 or older. For 2025, the standard catch-up was $3,500.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). SIMPLE IRA Contribution Limits by Year. Swoopr Investment. https://www.getswoopr.com/tables/retirement/simple-ira-contribution-limits/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.