
Direct Answer
The HSA contribution limit for 2026 is $4,400 for self-only HDHP coverage or $8,750 for family coverage. Those age 55 or older can contribute an additional $1,000 catch-up. You must be enrolled in a qualifying high-deductible health plan to contribute.
HSA Contribution Limits by Year
HSA limits, HDHP minimums, and out-of-pocket maximums (2010-2026)
OOPM = Out-of-pocket maximum. All amounts are IRS limits for qualifying HDHPs under IRC Section 223.
| Year | Self-Only Limit | Family Limit | Catch-up (55+) | Min. Deductible (Self) | Min. Deductible (Family) | OOPM (Self) | OOPM (Family) |
|---|---|---|---|---|---|---|---|
| 2010 | $3,050 | $6,150 | $1,000 | $1,200 | $2,400 | $5,950 | $11,900 |
| 2011 | $3,050 | $6,150 | $1,000 | $1,200 | $2,400 | $5,950 | $11,900 |
| 2012 | $3,100 | $6,250 | $1,000 | $1,200 | $2,400 | $6,050 | $12,100 |
| 2013 | $3,250 | $6,450 | $1,000 | $1,250 | $2,500 | $6,250 | $12,500 |
| 2014 | $3,300 | $6,550 | $1,000 | $1,250 | $2,500 | $6,350 | $12,700 |
| 2015 | $3,350 | $6,650 | $1,000 | $1,300 | $2,600 | $6,450 | $12,900 |
| 2016 | $3,350 | $6,750 | $1,000 | $1,300 | $2,600 | $6,550 | $13,100 |
| 2017 | $3,400 | $6,750 | $1,000 | $1,300 | $2,600 | $6,550 | $13,100 |
| 2018 | $3,450 | $6,900 | $1,000 | $1,350 | $2,700 | $6,650 | $13,300 |
| 2019 | $3,500 | $7,000 | $1,000 | $1,350 | $2,700 | $6,750 | $13,500 |
| 2020 | $3,550 | $7,100 | $1,000 | $1,400 | $2,800 | $6,900 | $13,800 |
| 2021 | $3,600 | $7,200 | $1,000 | $1,400 | $2,800 | $7,000 | $14,000 |
| 2022 | $3,650 | $7,300 | $1,000 | $1,400 | $2,800 | $7,050 | $14,100 |
| 2023 | $3,850 | $7,750 | $1,000 | $1,500 | $3,000 | $7,500 | $15,000 |
| 2024 | $4,150 | $8,300 | $1,000 | $1,600 | $3,200 | $8,050 | $16,100 |
| 2025 | $4,300 | $8,550 | $1,000 | $1,650 | $3,300 | $8,300 | $16,600 |
| 2026 | $4,400 | $8,750 | $1,000 | $1,700 | $3,400 | $8,500 | $17,000 |
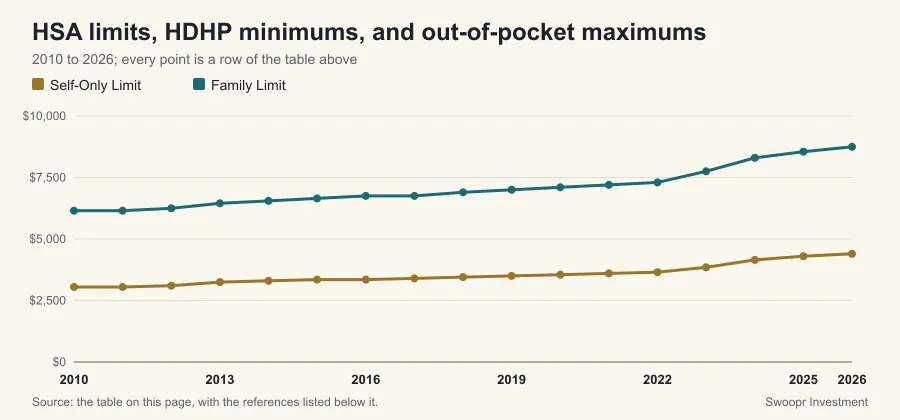
Source: IRS Publication 969: Health Savings Accounts and Other Tax-Favored Health Plans. Last verified: September 2026. Verify current-year figures at IRS.gov before making decisions.
Frequently asked questions
What are the HSA contribution limits for 2026?
For 2026, the HSA contribution limit is $4,400 for self-only coverage or $8,750 for family coverage. People age 55 or older can contribute an additional $1,000 catch-up contribution. You must be enrolled in a qualifying HDHP to contribute to an HSA.
Can I use HSA funds for non-medical expenses?
You can withdraw HSA funds for non-medical expenses without penalty once you reach age 65. Before that, non-qualified withdrawals are subject to income tax plus a 20% penalty. After age 65, non-qualified withdrawals are taxed as ordinary income but carry no penalty, making the HSA behave like a traditional IRA.
What is a triple tax advantage?
HSAs offer three tax benefits: contributions are tax-deductible (or pre-tax via payroll), earnings grow tax-free, and qualified medical withdrawals are tax-free. No other commonly available account offers all three. Many financial planners recommend maximizing HSA contributions and investing them for long-term growth rather than spending them on current medical costs.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). HSA Contribution Limits by Year. Swoopr Investment. https://www.getswoopr.com/tables/retirement/hsa-contribution-limits/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.