
Direct Answer
Long-term capital gains (assets held more than one year) are taxed at 0%, 15%, or 20% depending on taxable income. For 2026, the 0% rate applies to single filers with taxable income up to $49,450 and married joint filers up to $98,900, up from $48,350 and $96,700 in 2025. The 20% rate applies to the highest earners. An additional 3.8% net investment income surtax may also apply.
Long-Term Capital Gains Tax Rates by Income
2026 long-term capital gains rates by filing status
| Filing Status | 0% Rate Threshold | 15% Rate Range | 20% Rate Begins |
|---|---|---|---|
| Single | Up to $49,450 | $49,451-$545,500 | Over $545,500 |
| Married Filing Jointly | Up to $98,900 | $98,901-$613,700 | Over $613,700 |
| Head of Household | Up to $66,200 | $66,201-$579,600 | Over $579,600 |
| Married Filing Separately | Up to $49,450 | $49,451-$306,850 | Over $306,850 |
| Estates and Trusts | Up to $3,300 | $3,301-$16,250 | Over $16,250 |
Source: IRS: Rev. Proc. 2025-32 (section 4.03) and IRS: Topic No. 409 Capital Gains and Losses. Last verified: October 2026. Verify current-year figures at IRS.gov before making decisions.
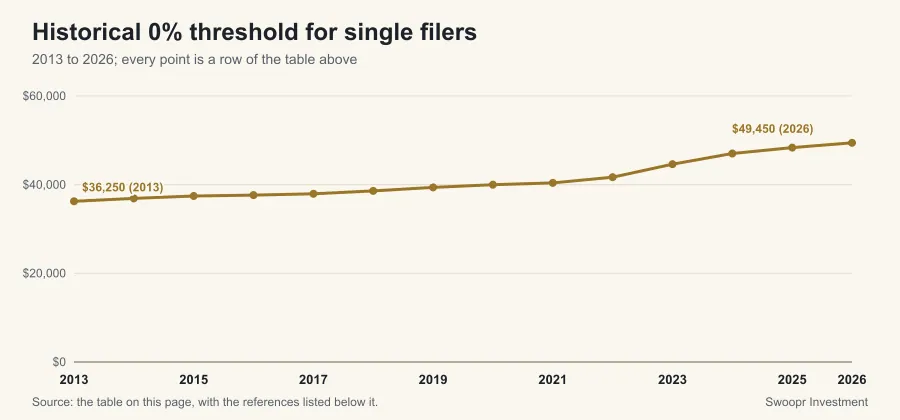
Historical 0% threshold for single filers (2013-2026)
| Year | Single Filer 0% Threshold |
|---|---|
| 2013 | $36,250 |
| 2014 | $36,900 |
| 2015 | $37,450 |
| 2016 | $37,650 |
| 2017 | $37,950 |
| 2018 | $38,600 |
| 2019 | $39,375 |
| 2020 | $40,000 |
| 2021 | $40,400 |
| 2022 | $41,675 |
| 2023 | $44,625 |
| 2024 | $47,025 |
| 2025 | $48,350 |
| 2026 | $49,450 |
Note on taxable income vs. MAGI
Capital gains rate thresholds use taxable income (after deductions), not MAGI. The 3.8% NIIT threshold uses MAGI. These are different figures: a retiree with $60,000 of Social Security income may have MAGI above $200,000 while still having taxable income in the 0% capital gains bracket after deductions.
Frequently asked questions
What qualifies for the 0% long-term capital gains rate?
Assets held more than one year qualify as long-term. In 2026, single filers with taxable income up to $49,450 pay 0% on long-term capital gains (up from $48,350 in 2025). Taxable income is your AGI minus the standard or itemized deduction. If your ordinary income is low, as in early retirement before Social Security, you may be able to realize capital gains entirely in the 0% bracket.
What is the additional 3.8% net investment income tax?
The 3.8% Net Investment Income Tax (NIIT) applies to the lesser of net investment income or the amount by which MAGI exceeds $200,000 (single) or $250,000 (MFJ). It stacks on top of the capital gains rate. A single filer with $600,000 income faces a 20% capital gains rate plus 3.8% NIIT for an effective 23.8% on investment income above the threshold.
What is the difference between short-term and long-term capital gains?
Short-term capital gains apply to assets held one year or less and are taxed at ordinary income tax rates (up to 37% in 2026). Long-term gains apply to assets held more than one year and qualify for the preferential 0%, 15%, or 20% rates. Holding an investment one day beyond the one-year mark can significantly reduce the tax on the gain.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). Long-Term Capital Gains Tax Rates by Income. Swoopr Investment. https://www.getswoopr.com/tables/retirement/capital-gains-tax-rates/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.