
Direct Answer
The 457(b) employee deferral limit for 2026 is $24,500. Workers age 50 or older can add a $8,000 catch-up. Within three years of normal retirement age, the special double-limit catch-up allows up to $49,000 in 2026. Governmental 457(b) assets can be rolled to IRAs; non-governmental plans generally cannot.
457(b) Contribution Limits by Year
457(b) contribution limits by year (2015-2026)
The 3-year special catch-up cannot be combined with the age-50 catch-up in the same year. It allows contributions up to twice the standard annual limit.
| Year | Employee Deferral | Catch-up (Age 50+) | Special 3-Year Catch-up (Max) |
|---|---|---|---|
| 2015 | $18,000 | $6,000 | $36,000 |
| 2016 | $18,000 | $6,000 | $36,000 |
| 2017 | $18,000 | $6,000 | $36,000 |
| 2018 | $18,500 | $6,000 | $37,000 |
| 2019 | $19,000 | $6,000 | $38,000 |
| 2020 | $19,500 | $6,500 | $39,000 |
| 2021 | $19,500 | $6,500 | $39,000 |
| 2022 | $20,500 | $6,500 | $41,000 |
| 2023 | $22,500 | $7,500 | $45,000 |
| 2024 | $23,000 | $7,500 | $46,000 |
| 2025 | $23,500 | $7,500 | $47,000 |
| 2026 | $24,500 | $8,000 | $49,000 |
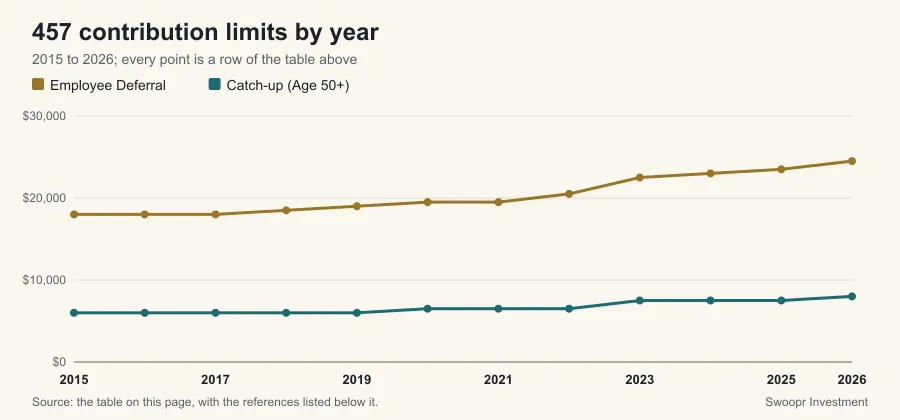
Source: IRS: IRC 457(b) Deferred Compensation Plans. Last verified: September 2026. Verify current-year figures at IRS.gov before making decisions.
Governmental vs. non-governmental 457(b)
Governmental 457(b) plans are held in trust and behave similarly to 401(k)s. Non-governmental 457(b) plans (offered by non-profit hospitals and charities) are unsecured promises of the employer, carry creditor risk, and generally cannot be rolled to an IRA. Verify your plan type before making distribution or rollover decisions.
Frequently asked questions
What is a 457(b) plan?
A 457(b) is a deferred compensation plan offered by state and local governments and certain nonprofits. Unlike 401(k) or 403(b) plans, the 457(b) contribution limit is separate: an employee can max out both a 403(b) and a 457(b) independently, doubling the tax-deferred savings opportunity.
What is the special 3-year catch-up provision?
Within three years of the plan's normal retirement age, 457(b) participants may contribute up to twice the standard annual limit. This allows employees to make up for prior years when they contributed less than the maximum. The additional amount equals the lesser of twice the annual limit or the prior-year undercontributions.
Can 457(b) funds be rolled over to an IRA?
Governmental 457(b) plan assets can be rolled to a traditional IRA, Roth IRA (with taxation), 401(k), or 403(b). Non-governmental 457(b) plans have significant restrictions: they are unfunded promises of the employer and generally cannot be rolled to an IRA or other qualified plan.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). 457(b) Contribution Limits by Year. Swoopr Investment. https://www.getswoopr.com/tables/retirement/457b-contribution-limits/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.