
Direct Answer
U.S. CPI inflation peaked at 9.1% in June 2022, the highest since November 1981. It declined to 2.7% by December 2025 (December over December). The Fed's 2% inflation target was first achieved in 2012 and maintained roughly 2012-2021, before the pandemic-era supply and demand shock drove the spike. Average CPI inflation since 2000 has been approximately 2.6%.
U.S. CPI Inflation History (Annual Rate)
U.S. CPI Annual Inflation Rate (Selected Years, 1980-2025)
| Year | Annual CPI Change (%) |
|---|---|
| 1980 | 13.5% |
| 1981 | 10.3% |
| 1982 | 6.2% |
| 1985 | 3.6% |
| 1990 | 5.4% |
| 1995 | 2.8% |
| 2000 | 3.4% |
| 2005 | 3.4% |
| 2009 | -0.4% |
| 2010 | 1.6% |
| 2011 | 3.2% |
| 2012 | 2.1% |
| 2013 | 1.5% |
| 2014 | 1.6% |
| 2015 | 0.1% |
| 2016 | 1.3% |
| 2017 | 2.1% |
| 2018 | 2.4% |
| 2019 | 1.8% |
| 2020 | 1.2% |
| 2021 | 4.7% |
| 2022 | 8.0% |
| 2023 | 4.1% |
| 2024 | 2.9% |
| 2025 | 2.6% |
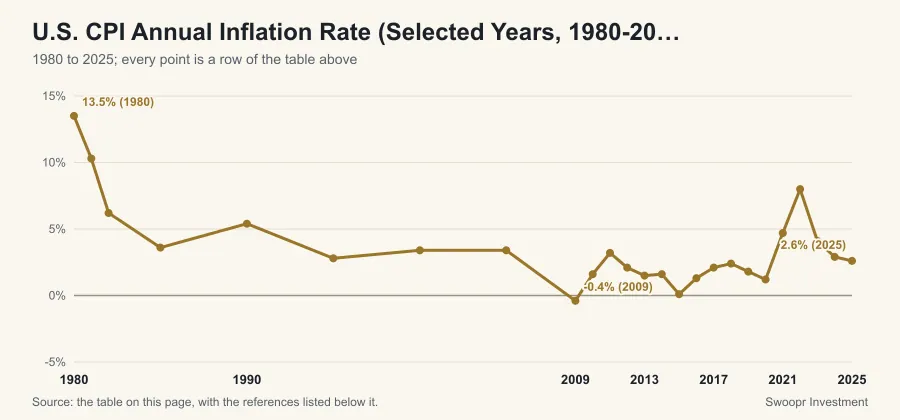
Source: St. Louis Fed FRED: Consumer Price Index. Last verified: October 2026, annual averages checked against BLS series CUUR0000SA0.
Frequently asked questions
What caused the 2021-2022 inflation surge?
The 2021-2022 inflation surge reflected multiple simultaneous shocks: (1) massive fiscal stimulus ($5+ trillion in COVID relief spending 2020-2021) boosted demand far beyond normal; (2) supply chain disruptions (factory closures, shipping container shortages, semiconductor shortages) constrained supply; (3) labor market dislocations (early retirements, worker shortages) raised wages and service costs; (4) housing shortage and rent inflation from pandemic migration patterns; (5) energy price spike from the Russia-Ukraine war (February 2022). The simultaneous demand surge and supply disruption was unprecedented in modern economic history.
What is core CPI vs. headline CPI?
Headline CPI includes all items. Core CPI excludes food and energy because these are volatile and subject to supply shocks unrelated to underlying demand. The Fed focuses on core PCE (Personal Consumption Expenditures) as its preferred inflation measure, rather than core CPI. Core PCE weights differ from CPI (less weight on housing, more on healthcare). In 2022-2023, the Fed focused on 'supercore' inflation (core services ex-housing), which tracked more closely to wage growth and demand-driven inflation. Core inflation typically provides a better signal for monetary policy than headline inflation.
How does inflation affect investments?
Inflation effects on major asset classes: (1) Stocks -- moderate inflation is generally compatible with positive stock returns (companies can raise prices); high unexpected inflation hurts stocks by raising discount rates; (2) Bonds -- inflation erodes fixed income real returns; TIPS protect against inflation; (3) Real estate -- physical assets often appreciate with inflation; REITs can raise rents; (4) Gold and commodities -- historically hedge unexpected inflation; (5) Cash -- severely damaged by inflation (purchasing power erodes at inflation rate). The worst investment environment for most portfolios is stagflation (high inflation + slow/negative growth), like 1973-74 and 1980.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). U.S. CPI Inflation History (Annual Rate). Swoopr Investment. https://www.getswoopr.com/tables/economy/us-inflation-cpi-history/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.