
Direct Answer
The 10-year U.S. Treasury yield is the benchmark long-term interest rate in the United States. Its daily constant-maturity rate peaked at 15.84% on September 30, 1981, fell to a record low of 0.52% on August 4, 2020, and closed 2024 at 4.58% and 2025 at 4.18%. This table lists year-end values; the annual averages are on the Investment Data Library page, and the two measure different things.
10-Year Treasury Yield History
10-Year Treasury Yield at Year End (Selected Years)
| Year | 10-Yr Yield (Year End) |
|---|---|
| 1980 | 12.43% |
| 1981 | 13.98% |
| 1982 | 10.36% |
| 1985 | 9.00% |
| 1990 | 8.08% |
| 1995 | 5.58% |
| 2000 | 5.12% |
| 2005 | 4.39% |
| 2007 | 4.03% |
| 2008 | 2.25% |
| 2009 | 3.84% |
| 2010 | 3.29% |
| 2011 | 1.88% |
| 2012 | 1.76% |
| 2013 | 3.03% |
| 2014 | 2.17% |
| 2015 | 2.27% |
| 2016 | 2.45% |
| 2017 | 2.41% |
| 2018 | 2.69% |
| 2019 | 1.92% |
| 2020 | 0.93% |
| 2021 | 1.52% |
| 2022 | 3.88% |
| 2023 | 3.88% |
| 2024 | 4.58% |
| 2025 | 4.18% |
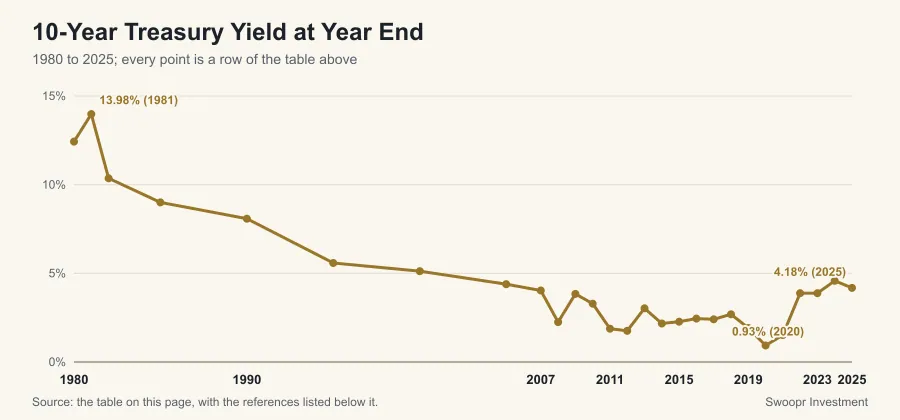
Source: St. Louis Fed FRED: 10-Year Treasury Rate. Last verified: October 2026, year-end values checked against FRED series DGS10.
Frequently asked questions
What does the 10-year Treasury yield tell us?
The 10-year Treasury yield is the risk-free rate benchmark for the U.S. economy. It reflects: (1) Federal Reserve policy (short-term rates influence but don't control the 10-year); (2) inflation expectations (higher expected inflation pushes yields up because investors demand compensation); (3) economic growth outlook (stronger growth pushes yields up); (4) global capital flows (international investors buying Treasuries push yields down). The 10-year yield directly affects mortgage rates (30-year fixed mortgages track the 10-year), corporate borrowing costs, and equity valuations (higher yields mean a higher discount rate, reducing stock values).
Why did the 10-year yield spike in 2022?
The 10-year yield rose from 1.52% (end 2021) to 3.88% (end 2022), a 236 basis point rise in one year. The cause: the Federal Reserve raised the federal funds rate by 425 basis points in 2022 to combat 9.1% CPI inflation, the highest since 1981. The Fed's aggressive rate hikes signaled that inflation was a sustained problem, pushing long-term yields higher as investors demanded inflation compensation. The full impact: the 30-year Treasury fell -39%, the Bloomberg US Aggregate Bond Index fell -13%, and mortgage rates doubled from approximately 3% to approximately 7%.
How does the 10-year yield affect stock valuations?
Higher 10-year yields reduce stock valuations through the discount rate mechanism. In discounted cash flow (DCF) models, future earnings are discounted at a rate that includes the risk-free rate (10-year Treasury). Higher risk-free rates mean future earnings are worth less in today's dollars. This effect is largest for long-duration stocks (high-growth companies with earnings far in the future). Technology stocks (long-duration) fell more than value/dividend stocks (shorter duration) in 2022 precisely because of this mechanism. The equity risk premium (expected stock return minus 10-year yield) also determines relative attractiveness: when yields rise to 4-5%, stocks become less relatively attractive versus risk-free bonds.
Worked Example: What a Year-End Move Does to a Note Bought at Par
Suppose a ten-year note was bought at par at the end of 2021 with a 1.52% coupon, the year-end yield in the table. By the end of 2022 the yield was 3.88%. Repricing the note's remaining cash flows at 3.88% (annual coupons, ten years left, for arithmetic clarity) gives a price of about 80.7 per 100 of face: a 19.3% price fall from a 236 basis point rise, with only 1.52 points of coupon income to set against it. That is the 2022 bond-market loss the FAQ describes, in one position.
The same arithmetic runs the other way. A note bought at par at the end of 2007 with a 4.03% coupon, repriced at the end-2008 yield of 2.25%, is worth about 115.8: a 15.8% gain in a year when stocks fell by more than a third, which is the flight-to-safety behaviour that made Treasuries the diversifier of that cycle. The sensitivity in both cases is duration: the lower the starting yield, the longer the duration and the larger the price move per point of yield change, so the 2021 note was more exposed to a given rise than the 2007 note would have been.
Cite This Page
If you reference this table in your own work, use the following citation format and add the date you accessed it:
Swoopr Editorial Team. (2026). 10-Year Treasury Yield History. Swoopr Investment. https://www.getswoopr.com/tables/bonds/10-year-treasury-yield-history/
Check the figures against the primary sources listed under References before you rely on or republish them; the series they come from are revised.